Self - Credit Builder & Cards

Screenshots
Details
- Rating
- 38.49K reviews
- Version
- 9.0.0
- Developer
- Self Financial, Inc.
Analysis by Norviv
Building credit can feel like a frustrating loop: lenders want to see a credit history before offering useful products, but creating that history usually requires access to credit in the first place. I tested Self - Credit Builder & Cards with that problem in mind, and its central idea is easy to understand: it gives people a way to work toward credit progress without starting with a traditional credit check. That makes it more focused than a general banking app and more deliberate than simply applying for another card.
What I like most is that the app is designed around a gradual process rather than instant access to borrowed money. You are not opening it to manage every part of your financial life. You are using it as a structured tool while trying to establish or strengthen a credit profile. That distinction matters, because the experience is most useful when you treat it as a long-term routine, not as a quick fix.
Self is a free finance app from Self Financial, Inc., available to an Everyone-rated audience. It has been around since March 30, 2018, and its current version is 9.0.0. With an average rating of 4.7 from around 102 thousand ratings and more than one million installs, it has clearly attracted a substantial audience. Those figures do not replace careful reading of the terms inside the app, but they do suggest that the basic concept has found a real need.
Why the credit-building approach matters
The app’s defining capability is the chance to build credit and work toward a credit card without a credit check at the starting point. In practical terms, that changes the first question you have to ask. Instead of wondering whether you will qualify for a conventional card immediately, you can focus on whether a structured credit-building product fits your budget and your timeline.
I see this as especially relevant for someone with a thin credit file, a limited borrowing history, or a past problem that makes ordinary applications uncomfortable. A standard card may be useful once you qualify, but repeated applications can be stressful and may not produce the result you want. Self presents a different route: begin with a product whose purpose is credit development, then consider the card side as your situation evolves.
That purpose also sets a realistic expectation. The app is not a magic button that transforms a credit profile overnight. Credit-building depends on responsible payments and the way accounts are reported and evaluated over time. The useful effect is the structure: it gives you a dedicated place to monitor the process instead of treating credit improvement as an abstract goal.
There is an important psychological benefit here. When credit repair is vague, it is easy to postpone it or make random applications. A focused app can turn the goal into a repeatable habit. I would still approach every payment obligation cautiously, but I appreciate that the product encourages planning rather than impulse.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
What the no-check starting point does and does not mean
The absence of a credit check for getting started should not be confused with free credit or guaranteed approval for every later product. It removes one common barrier at the entry stage, but it does not erase the need to understand eligibility, account conditions, payment responsibilities, or any requirements attached to a card option.
This is one of the first details I would explain to a friend. “No credit check required” sounds simple, but the right interpretation is narrower: the app is intended to help you begin a credit-building path without relying on a conventional initial credit decision. You still need enough income and financial discipline to handle the commitment responsibly.
I would also avoid viewing the app as a replacement for a complete financial plan. It can support a credit goal, but it does not automatically solve high-interest debt, irregular income, or spending that is already difficult to control. If your priority is budgeting, bill negotiation, investing, or everyday banking, a different finance app may be a better primary tool.
Using the app as a routine instead of a one-time download
In my experience, the best way to approach Self is to create a small review routine. I would open the app on a regular day, check the current status of the credit-building arrangement, confirm upcoming responsibilities, and make sure the linked payment plan still fits the month ahead. This is more useful than checking repeatedly whenever anxiety appears.
A practical tip is to connect the process to an existing financial habit, such as reviewing your account after receiving income or paying household bills. The app’s value is easier to see when it becomes part of a predictable sequence: check the obligation, compare it with your budget, and keep enough money available before the due date. That workflow reduces the risk of treating a credit-building payment as an afterthought.
Another useful habit is to keep notes about why you started. If the goal is eventually to qualify for better borrowing terms, rent a home more comfortably, or simply establish a usable history, writing that down can prevent you from judging the app by short-term changes. Credit progress is a patient project, and the app makes more sense when you use it with that time horizon.
A realistic everyday scenario
Imagine someone who has recently become financially independent but has almost no credit history. They want to work toward a card, yet a conventional application feels premature. Instead of submitting applications at random, they use Self to start a credit-building path, set a monthly reminder, and review the account before other discretionary spending.
In that situation, the app’s main benefit is not entertainment or convenience in the usual sense. It is organization. The user has one clearly defined credit task, a reason to monitor it, and a way to think about the next stage without immediately relying on a traditional card. If a payment would make the month difficult, the correct response is to reconsider the commitment rather than stretch the budget just to chase a credit goal.
For someone rebuilding after missed payments, the same structure may be helpful but more demanding. They need to prioritize every due date and avoid adding obligations they cannot comfortably manage. Self can support the rebuilding intention, but it cannot make poor cash-flow decisions safe. That is why I would pair the app with a basic spending plan, even if that plan is only a simple weekly check.
Where it differs from ordinary credit cards
A conventional credit card is usually built for flexible spending, rewards, and short-term payment convenience. Self is more purpose-driven. Its appeal comes from the credit-building path and the possibility of working toward a card, not from encouraging you to spend more or compare a long menu of everyday banking tools.
That makes it a better fit for a person whose first goal is establishing credit, while a mainstream card may be better for someone with a solid history who wants rewards, travel benefits, or a higher spending limit. A secured card can also be a stronger alternative for users who want direct revolving credit and already understand how to keep utilization and payments under control.
The trade-off is that a focused product may feel limited if you expect a full financial dashboard. I would not choose Self as my only finance app simply because its purpose is narrower. I would choose it when the narrow purpose is exactly what I need and when I want to avoid applying for products that do not match my current credit position.
The card goal requires patience and careful reading
Working toward a card is motivating, but I would not treat that possibility as an automatic reward for downloading the app. The sensible approach is to use the credit-building stage responsibly, watch how your circumstances change, and review the card details when an offer or eligibility path becomes relevant.
Before accepting anything, I would look closely at the cost of using the card, payment expectations, and how it fits with other accounts. The app may make the next step easier to consider, but you remain responsible for deciding whether that step is genuinely affordable. A card should serve a stable plan, not become a way to cover a recurring shortfall.
This is also where the app may disappoint users who want immediate access to a conventional line of credit. If you need a card today for a specific purchase or emergency, a credit-building route may feel too slow. In that case, comparing a secured card, a credit union option, or another product that clearly matches your immediate need could make more sense.
Small workflow choices that improve the experience
I found three practical choices especially valuable. First, I would set aside the expected payment before spending on optional items. That turns the credit obligation into a priority rather than something left over at the end of the month.
Second, I would avoid opening several unrelated credit products at the same time simply because I am trying to improve quickly. The app works best as a measured path. Adding multiple applications can make your finances harder to follow and may undermine the calm, deliberate approach that makes a credit-builder useful.
Third, I would review progress in context. A credit score or account change is only one part of financial health. I would also ask whether payments are comfortable, whether savings are growing, and whether the account is helping me make better decisions. If the answer to those questions is no, the problem may be the budget rather than the app.
These points are easy to overlook because the store summary is short. The real advantage is not merely that the app mentions credit building. It is that the product gives the goal a dedicated workflow. The real risk is also in that workflow: a structured payment is still a financial responsibility, and structure does not make an unaffordable commitment affordable.
Who will gain the most from it
I think Self is strongest for adults who are starting with limited credit information and want a guided, purpose-specific route toward a stronger profile. It can also suit someone who feels uncomfortable applying for ordinary cards before understanding their options. The free download lowers the barrier to exploring the service, while the Everyone age rating makes it broadly accessible from a content perspective.
It is less suitable for a person who already has excellent credit and mainly wants premium rewards, travel perks, or a sophisticated spending-management system. That user may gain more from comparing established card issuers directly. It is also not the right choice for someone who cannot reliably meet a recurring payment, even if the credit goal feels urgent.
People with unstable income should be especially careful. A credit-building plan can be worthwhile, but only after essential expenses and a small safety margin are protected. If one unexpected bill could cause a missed payment, I would delay starting until the monthly commitment is genuinely manageable. Protecting financial stability matters more than pursuing a credit milestone.
Those who prefer hands-on research may also want to compare Self with secured cards and local financial institutions before deciding. The app is convenient as a focused starting point, but convenience should not replace checking the total cost and conditions. The best option depends on whether your priority is beginning without a credit check, getting direct card access, or finding the lowest overall cost.
My experience with the app’s overall position
After using it as a credit-focused finance tool, I came away with a clear impression: Self is most valuable when you need a starting structure, not when you need a complete financial command center. Its central capability gives people with limited credit history a less intimidating entry point, and the path toward a card provides a concrete reason to stay engaged.
The app’s popularity is reflected in its 4.7 average and roughly 38 thousand written reviews, while its free price makes it easy to investigate without paying for the download itself. I would still judge the service by the obligations attached to the account rather than by the app’s price alone. Free access does not mean every financial product connected with the experience has no cost.
On my device, the stated minimum operating-system requirement is Android 7.0 or later, which keeps it accessible to many older Android phones. The current release, 9.0.0, is worth checking against your phone before installing, especially if you use an older device. That is a small practical step, but it prevents confusion when an otherwise suitable finance app cannot be installed or updated.
The decision I would make
I would recommend Self to a friend who has a thin credit file, wants to avoid a conventional credit check at the beginning, and can commit to a careful payment routine. I would explain that the app is a tool for building a foundation, not a shortcut to instant approval or a substitute for budgeting.
I would not recommend it automatically to someone who already qualifies for better card products, needs immediate borrowing flexibility, or is struggling to cover essential bills. For those users, another option may be cheaper, faster, or safer. The right question is not whether credit building sounds useful in general; it is whether this particular structured path fits the person’s current cash flow and actual goal.
My final view is positive but measured. Self makes a difficult first step feel more organized, and its focus on building credit without a starting credit check is genuinely meaningful for the right user. The strongest result comes from treating it as a disciplined financial routine, not as a promise of instant credit improvement. If you can afford the responsibility and want a clear route toward a stronger credit profile and possible card access, it is a sensible app to consider.
Frequently Asked Questions
01What is Self - Credit Builder & Cards, and how does it work?
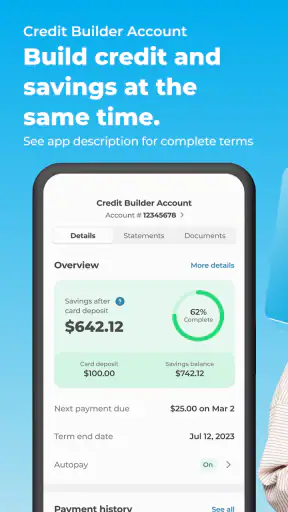
Self - Credit Builder & Cards is a financial app designed to help eligible users build or establish credit through a Credit Builder Account and, in some cases, a secured credit card. Instead of receiving a traditional loan upfront, you generally make scheduled payments into an account while payment activity may be reported to major credit bureaus. The exact product, terms, fees, and approval requirements can vary by applicant.
02Can Self - Credit Builder & Cards improve my credit score?
The app may help support credit-building efforts when your account activity is reported to participating credit bureaus and you make every payment on time. However, Self cannot guarantee a specific score increase because credit scores also depend on your existing accounts, balances, payment history, credit age, and other factors. Late or missed payments may negatively affect your credit, so users should review the agreement carefully before enrolling.
03Does the Self app require a credit check or good credit?
Self is intended for people who may have limited, damaged, or no established credit, so approval may be more accessible than with some conventional credit products. Nevertheless, you still need to meet eligibility and identity-verification requirements, and certain products may involve a review of your information. Approval is not guaranteed, and availability can depend on your state, financial profile, and the specific account you apply for.
04What fees and costs should I expect when using Self?
Before opening an account, carefully check the current pricing because costs can include an administrative or account fee, monthly payments, interest, card fees, and possible charges for late payments or other services. The total amount and payment schedule depend on the selected plan and product. Reading the disclosures in the app is important, since a credit-building account is not free and the terms may change over time.
05Is the Self secured credit card available to everyone?
No. The Self secured credit card is not automatically available to every app user. Eligibility may require an active Self Credit Builder Account in good standing, completion of verification, and satisfaction of additional approval conditions. If approved, the card typically uses available funds or account savings as security for the credit line. Users should confirm current requirements, limits, fees, and application terms directly in the app.


